


August liquidity events related to portfolio companies in which PIF invests through its private equity holdings.
Realized distributions turn paper gains into cash that can be redeployed into new investments to drive future returns. Pomona Investment Fund (PIF) is built around this dynamic.
By purchasing fund interests later in their life cycles, PIF focuses on investments with greater visibility into near-term return of capital. As distributions are received, that capital is recycled into new opportunities.
Below, we highlight select recent exit transactions from PIF, illustrating why liquidity matters in private equity investing. (Learn more about the importance of liquidity)
Distributions as a percent of total return1
PIF: 58%
Peer average: 29%
Colis Privé expands last-mile delivery business into Spain and Portugal
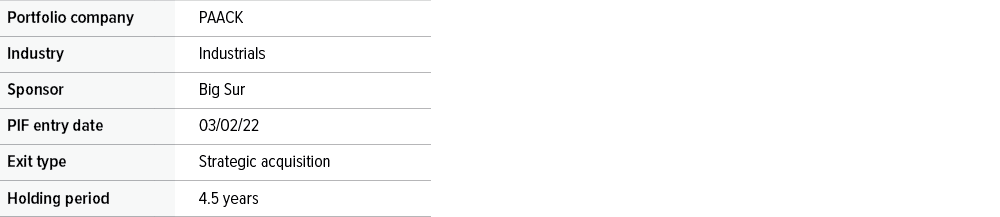
Global freight middleman Ceva Logistics completed the acquisition of couriers Paack Iberia and Paack France for integration into Colis Privé, its European last-mile delivery business.
About 490 employees will join Colis Privé through the transaction, which aims to strengthen the company’s domestic network in France while enabling it to expand into Spain and Portugal, two fast-growing e-commerce markets, the company announced last week.
Ceva Logistics, part of France-based conglomerate CMA CGM, originally announced the deal in late June.
Paack supports retailers with an extensive delivery network (82 transfer centers and more than 5,000 active pickup points) in the Iberian peninsula and six urban delivery stations in France, bringing packages to individual residences as well as out-of-home delivery points.
Based in the Aix-Marseille-Provence metropolitan area, Colis Privé relies on a national network of 56 sorting hubs and operational centers, as well as approximately 5,000 delivery drivers, to deliver parcels across France every day. In 2025, the acquisition of MIPI, which has more than 300 delivery drivers, strengthened its coverage of France’s major metropolitan areas. The company serves leading French and international e-commerce players and is also present in Belgium and Luxembourg.
H.I.G. Capital completes the sale of ECI
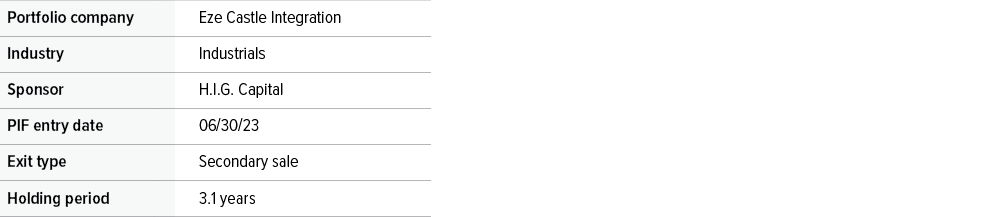
H.I.G. Capital, a global alternative investment firm with $75 billion of capital under management, announced the sale of its portfolio company, Eze Castle Integration (ECI), a global provider of enterprise technology services solutions to the alternative investment and regulated financial services industries, to Wind Point Partners.
Headquartered in New York, ECI is a managed services provider built specifically for alternative investment managers and investment banks, with more than 30 years serving highly regulated financial services clients. ECI delivers a holistic suite of managed IT, cybersecurity, and compliance services, complemented by innovative offerings in governance, risk, and compliance (GRC) and AI, through a global delivery platform spanning the US, UK, Europe, and Asia-Pacific. The company serves more than 630 clients across 37 countries, supported by a global team of more than 775 professionals and eight data center locations worldwide.
Following its acquisition of ECI, H.I.G. executed on its thesis to transform the company into a modern, security-first managed services platform. During H.I.G.’s ownership, ECI expanded its offering beyond core managed IT into holistic cybersecurity, GRC, and AI-enabled managed services to establish a scaled global delivery model. The company also deepened its position as the partner of choice for blue-chip financial services firms and extended its capabilities into adjacent regulated markets.
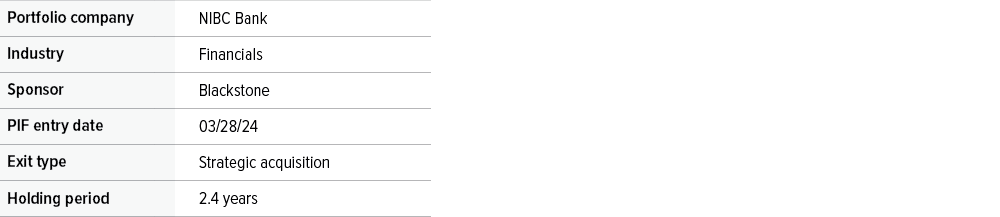
ABN AMRO completes acquisition of NIBC
ABN AMRO completed the acquisition of NIBC. With all closing conditions fulfilled, including regulatory approvals, the acquisition marks an important step in ABN AMRO’s strategy. It strengthens ABN AMRO’s banking activities, reinforcing its position in the Dutch retail market. In the coming period, NIBC and ABN AMRO will take the next steps towards integration.
The acquisition is fully aligned with ABN AMRO’s strategy. Together, NIBC and ABN AMRO will increase the scale of ABN AMRO’s position in the Dutch mortgage market, while also enhancing its presence in the savings markets of the Netherlands, Germany, and Belgium. In addition, the transaction will further reinforce the bank’s geographic position in key client segments, including corporate banking across its European footprint. The acquisition of NIBC also supports ABN AMRO’s streamlined brand strategy with its focus on its core brands, adding the strong NIBC brand to its mortgage portfolio, and combining NIBC’s savings business with ABN AMRO challenger BUX.
Established in 1945, NIBC is an entrepreneurial bank with a strong focus on the Dutch market and specializing in mortgage lending, savings products, commercial real estate, and digital infrastructure lending. NIBC serves approximately 325,000 savings clients, 200,000 mortgage clients, and 175 corporate clients all within ABN AMRO’s North-west European footprint.
Willkie advised CVC on sale of minority stake in Syntegon to Apollo
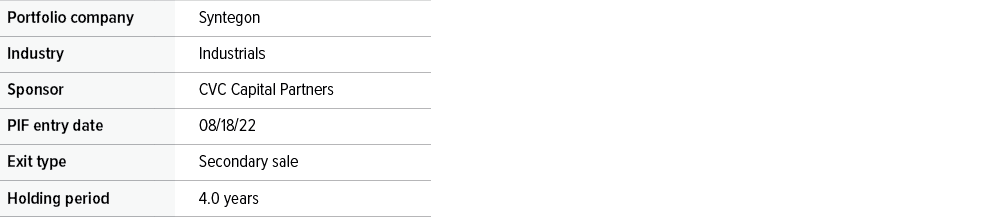
Willkie represented CVC Capital Partners in the sale of 37% of its stake in Syntegon, a technology company and strategic partner to the pharmaceutical, biotechnology, and food industries, to an investor group led by Apollo-managed funds.
The Apollo-led investor group acquired a 37% minority stake in Syntegon, with CVC retaining its majority stake with the remaining 63% of shares. The partnership is activated to accelerate Syntegon’s next growth phase including its expansion in the North American market.
Willkie previously advised CVC on its acquisition of Syntegon in 2020.
Syntegon, headquartered in Stuttgart, provides in-depth process expertise and mission-critical technologies to the pharmaceutical and biotechnology sectors for the production of essential medicines, as well as high-speed, high-precision packaging solutions for the food sector.
CVC is a global private markets manager with a network of 30 office locations throughout EMEA, the Americas, and Asia, with €205 billion of assets under management.
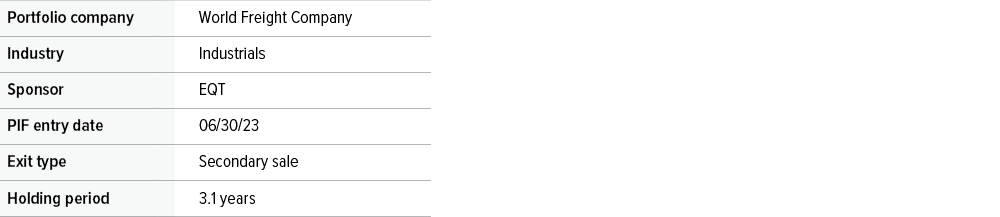
EQT and PAI Partners agree to sell World Freight Company
BPEA Private Equity Fund VI and PAI Partners announced that Brookfield, through its private equity business, agreed to acquire World Freight Company (WFC), a global air freight services provider, from EQT and PAI.
Founded in 2004, WFC is now one of the world’s largest general sales and service agents for the global air freight industry. The company represents airlines to sell and manage cargo capacity while coordinating key operational activities including booking, handling, and shipment oversight. WFC serves more than 300 airlines on 3,500 trade lanes and over 16,000 freight forwarders across more than 80 countries and key international trade routes.
Since partnering with WFC, EQT and PAI supported the company’s transformation into a scaled global platform through a combination of organic growth initiatives, strategic acquisitions, and continued investment in technology and digital capabilities. During this period, WFC expanded its international footprint, strengthened its operational infrastructure, and further enhanced its service offering to customers and airline partners worldwide.
Today, WFC plays an important role in the global air freight ecosystem, helping optimize efficiency and commercial outcomes across increasingly complex supply chains.
Types of liquidity events
- Continuation vehicle: A PE firm extends its holding period in a portfolio company through a new fund.
- IPO: A privately held company lists on a public exchange, converting the PE firm’s stake into publicly traded shares
- Recapitalization: A portfolio company issues debt to pay a dividend to the PE firm, generating returns prior to exit.
- Secondary sale: A PE firm sells its stake in a company to another PE firm.
- Strategic acquisition: Another company acquires the portfolio company, typically at a premium that reflects its strategic value.
Risk of investing Discussed below are the investments generally made by Investment Funds and the principal risks that the Adviser and the Fund believe are associated with those investments and with direct investments in operating companies. These risks will, in turn, have an effect on the Fund. In response to adverse market, economic or political conditions, the Fund may invest in investment grade fixed income securities, money market instruments and affiliated or unaffiliated money market funds or may hold cash or cash equivalents for liquidity or defensive purposes, pending investment in longer-term opportunities. In addition, the Fund may also make these types of investments pending the investment of assets in Investment Funds and Co-Investment Opportunities or to maintain the liquidity necessary to effect repurchases of Shares. When the Fund takes a defensive position or otherwise makes these types of investments, it may not achieve its investment objective. The value of the Fund’s total net assets is expected to fluctuate in response to fluctuations in the value of the Investment Funds, direct investments and other assets in which the Fund invests. An investment in the Fund involves a high degree of risk, including the risk that the Shareholder’s entire investment may be lost. The Fund’s performance depends upon the Adviser’s selection of Investment Funds and direct investments in operating companies, the allocation of offering proceeds thereto, and the performance of the Investment Funds, direct investments, and other assets. The Investment Funds’ investment activities and investments in operating companies involve the risks associated with private equity investments generally. Risks include adverse changes in national or international economic conditions, adverse local market conditions, the financial conditions of portfolio companies, changes in the availability or terms of financing, changes in interest rates, exchange rates, corporate tax rates and other operating expenses, environmental laws and regulations, and other governmental rules and fiscal policies, energy prices, changes in the relative popularity of certain industries or the availability of purchasers to acquire companies, and dependence on cash flow, as well as acts of God, uninsurable losses, war, terrorism, earthquakes, hurricanes or floods and other factors which are beyond the control of the Fund or the Investment Funds. Unexpected volatility or lack of liquidity, such as the general market conditions that prevailed in 2008, could impair the Fund’s performance and result in its suffering losses. The value of the Fund’s total net assets is expected to fluctuate. To the extent that the Fund’s portfolio is concentrated in securities of a single issuer or issuers in a single sector, the investment risk may be increased. The Fund’s or an Investment Fund’s use of leverage is likely to cause the Fund’s average net assets to appreciate or depreciate at a greater rate than if leverage were not used. The Fund is a non-diversified, closed-end management investment company with limited performance history that a Shareholder can use to evaluate the Fund’s investment performance. The Fund may be unable to raise substantial capital, which could result in the Fund being unable to structure its investment portfolio as anticipated, and the returns achieved on these investments may be reduced as a result of allocating all of the Fund’s expenses over a smaller asset base. The initial operating expenses for a new fund, including start-up costs, which may be significant, may be higher than the expenses of an established fund. The Investment Funds may, in some cases, be newly organized with limited operating histories upon which to evaluate their performance. As such, the ability of the Adviser to evaluate past performance or to validate the investment strategies of such Investment Funds will be limited. In addition, the Adviser has not previously managed the assets of a closed-end registered investment company. Closed-End Fund; Liquidity Risks. The Fund is a non-diversified closed-end management investment company designed principally for long-term investors and is not intended to be a trading vehicle. An investor should not invest in the Fund if the investor needs a liquid investment. Closed-end funds differ from open-end management investment companies (commonly known as mutual funds) in that investors in a closed-end fund do not have the right to redeem their shares on a daily basis at a price based on net asset value. |