

Fixed Income Perspectives: Rethinking Higher Rates in a Resilient Economy

Head of Multi-Sector Fixed Income

Key Takeaways
Unlike in 2022, today’s higher rates are more tied to resilient growth than an intensifying inflation shock.
Growth has remained robust despite higher rates and elevated energy prices, helping explain why long-term yields have moved higher.
Higher starting yields create more optionality for success in fixed income, supporting a diversified approach rather than positioning for a single rate scenario.
Many investors are still looking at fixed income through the lens of 2022. But today's combination of persistent growth and higher starting yields calls for a different playbook.
Same rates, different backdrop
After more than a decade of near-zero rates following the global financial crisis and pandemic-era policy support, investors experienced one of the most challenging periods for fixed income in a generation during the 2022-2023 bond market rout.
The recent bond selloff may revive memories of that period, but today’s economic and monetary policy backdrop is fundamentally different, making a repeat of 2022 unlikely.
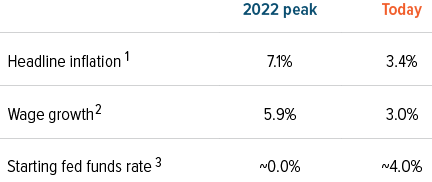
1 As of 08/31/26. Headline inflation is represented by headline PCE inflation. Source: U.S. Bureau of Economic Analysis.
2 As of 09/30/26. Wage growth is represented by average hourly earnings growth. Source: U.S. Bureau of Labor Statistics.
3 As of 09/30/26. Source: U.S. Federal Reserve.
In 2022, the backdrop was shaped by surging inflation, accelerating wage growth, and the Fed finally lifting rates off of zero. Today, inflation and wage pressures have eased considerably, and policy rates are already near 4%. While yields have risen again, the forces driving them are fundamentally different.
The biggest surprise isn’t inflation
Long-term yields have risen sharply in both periods. But today’s move appears increasingly tied to a different question: Why has the economy remained so resilient despite higher rates, elevated energy prices, and tighter financial conditions?
Historically, that combination would have raised concerns about a much sharper slowdown. Instead, growth has continued to surprise to the upside. That resilience has led markets to reassess not only the path of Fed policy but also the economy’s longer-term growth potential.
AI-related investment is one reason. Continued investment and steady demand have challenged the assumption that higher rates would quickly translate into weaker economic activity. As a result, higher yields may reflect stronger growth expectations as much as lingering inflation concerns.
So far, AI-related investment has helped support economic resilience. However, growth that depends heavily on a narrow set of drivers can also be fragile. If AI spending slows or delivers less economic benefit than investors currently expect, growth could soften and the recent rise in rates could reverse.
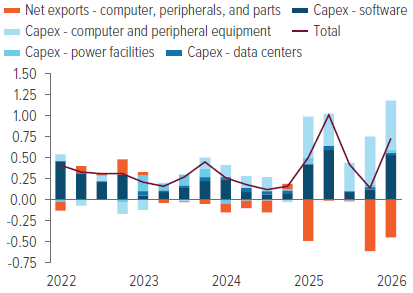
Source: “The AI Buildout and the Economy: Publicly Available Data to Assess AI’s Impact,” FEDS Notes, U.S. Bureau of Economic Analysis, 07/17/26.
A more balanced starting point
Today’s starting yields provide a much larger cushion than in 2022, when investors faced rising rates with little income and few offsets against additional volatility.
Higher yields in 2026 offer the potential for:
- More income: Higher starting yields create a larger source of return than investors had in 2022.
- More flexibility: Bonds no longer require falling rates to contribute meaningfully.
- More balance: Fixed income can help portfolios navigate a wider range of economic and market outcomes.
Importantly, whether growth slows, remains resilient, or accelerates, fixed income can contribute in different ways than it could during the 2022 bond market selloff.
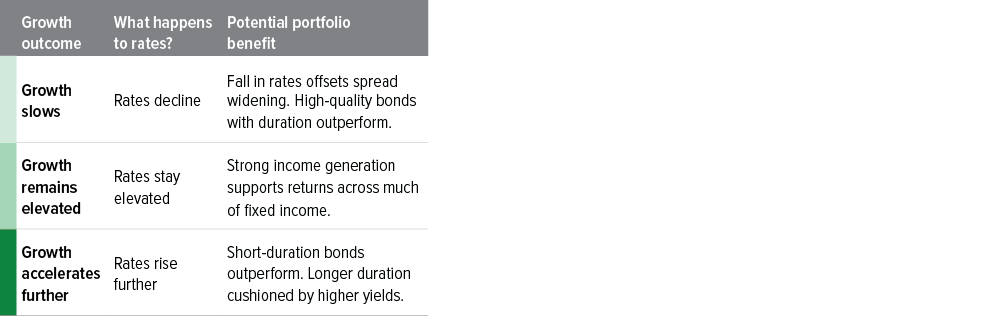
For illustrative purposes only
Today’s higher yield base also provides a meaningful buffer against rate uncertainty and can improve potential return outcomes across a range of scenarios.
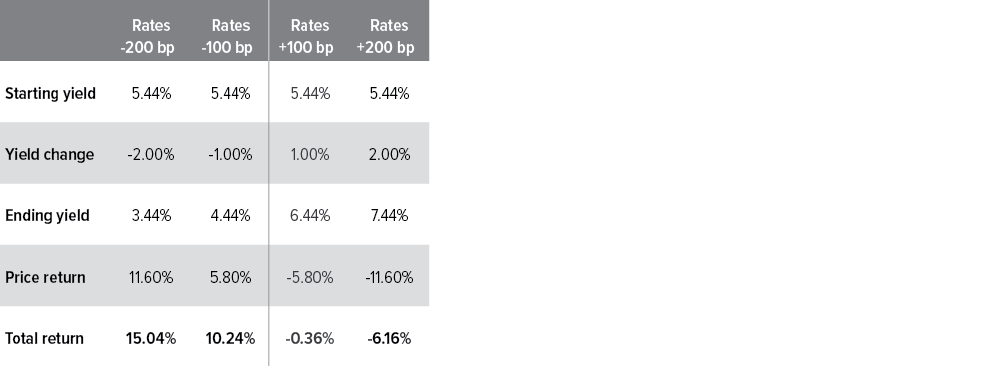
Hypothetical illustration based on a 5.44% starting yield and a duration of 5.8 years. Price returns are estimated using duration-based approximations and exclude convexity effects. Actual results will vary.
Even if yields move higher, income can offset a portion of price declines and make fixed income more resilient than many investors may assume.
A different playbook
In 2022, investors faced rising rates amid accelerating inflation, rapid wage growth, and a Fed that was beginning an aggressive tightening cycle from near-zero rates. At the same time, fixed income offered little income cushion if yields moved higher.
Today, inflation and wage pressures have moderated, policy rates are already near 4%, and higher starting yields can help portfolios navigate a wider range of scenarios.
The lesson from 2022 is not that investors should avoid fixed income whenever yields rise. It is that the drivers behind rising yields matter. And today’s backdrop looks very different.
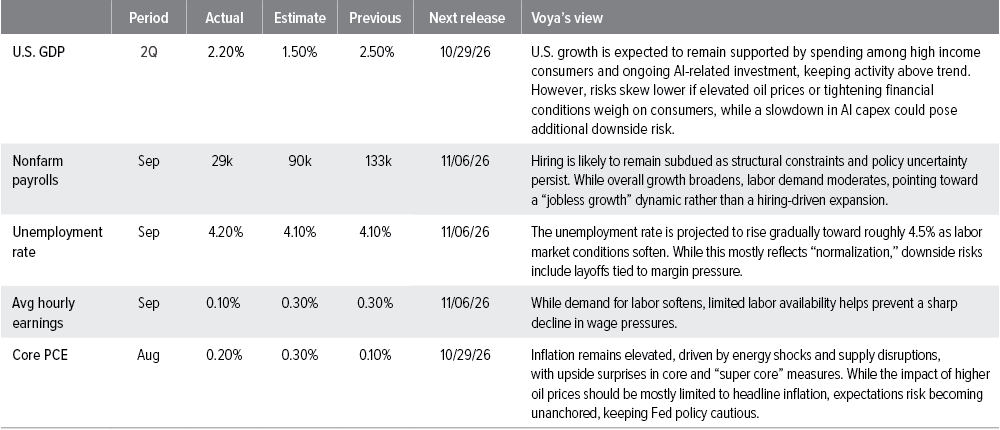
As of 10/22/26. Source: Bloomberg, FactSet, Bureau of Labor Statistics, Voya IM.
Sector scorecard
Credit spreads represent the extra yield over the 10-year Treasury.

1 Option-adjusted spreads (OAS) represent the extra yield over the Treasury yield curve, after adjusting for the value of any embedded options.
See back page for definitions.
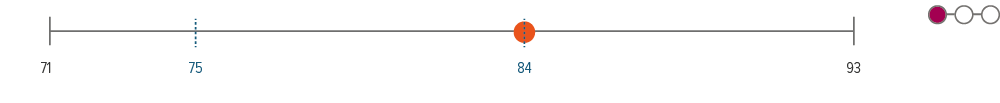
- Investment grade corporate bonds remain neutral/ negative, with spreads range-bound and valuations still not attractive enough to warrant broad risk addition.
- September supply of $198 billion fell short of a record, and October supply should slow, creating room for decent near-term performance if yields stabilize alongside supportive third-quarter earnings.
- We still see selective value in hybrids, BBBs, banks, utilities, TMT/AI-capex beneficiaries, and attractive new-issue concessions, but portfolios should stay close to index until valuations improve.
- High yield remains neutral, with supportive fundamentals and carry offset by tight valuations.
- Corporate fundamentals are still broadly constructive, earnings beats continue to outnumber misses, and defaults remain manageable, but stress is more visible in CCCs, cable/satellite, selected consumer and cyclical credits, and lower-income consumer exposures.
- Positioning should emphasize durable business models, low-BB to mid/high-B risk, and selective carry, while remaining underweight vulnerable cyclicals, lower-quality CCCs, structurally challenged media/cable, telecom, technology, transportation, and energy E&P.
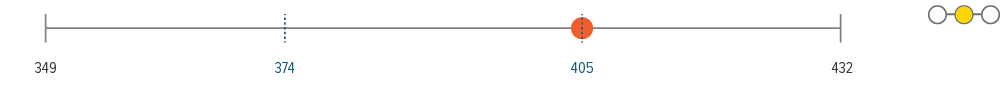
- Senior loans remain constructive, supported by strong technicals, stable fundamentals, belowaverage payment defaults, and attractive carry, but tight valuations are challenging.
- September delivered a positive return, helped by a continued rebound in software loans, a deepening supply shortage, and $14 billion of CLO issuance, though CCC loans remained negative and dispersion stayed high.
- Positioning should retain an up-in-quality bias, favoring low-BB and mid-single-B risk while staying selective around software/SaaS, autos, chemicals, consumer discretionary, media, and weaker lowsingle- B or CCC issuers exposed to AI disruption or refinancing pressure.
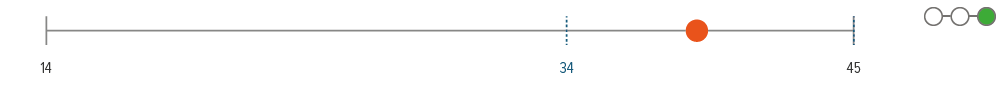
- Agency MBS have moved to modestly positive tactically, as spreads have widened in response to rate volatility.
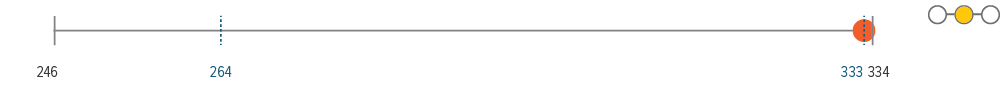
- Current-coupon OAS was 7 bp wider at 33 and ZV was 16 bp wider at 109, with both wider than their 12-month averages; muted organic supply, low cashout refinancing, and potential GSE purchase demand remain medium-term tailwinds.
- Key risks include a continued Treasury selloff, renewed rate volatility shocks, disappointing GSE purchase execution, bank and overseas buyer hesitation, fast money or REIT selling, and policy headlines.
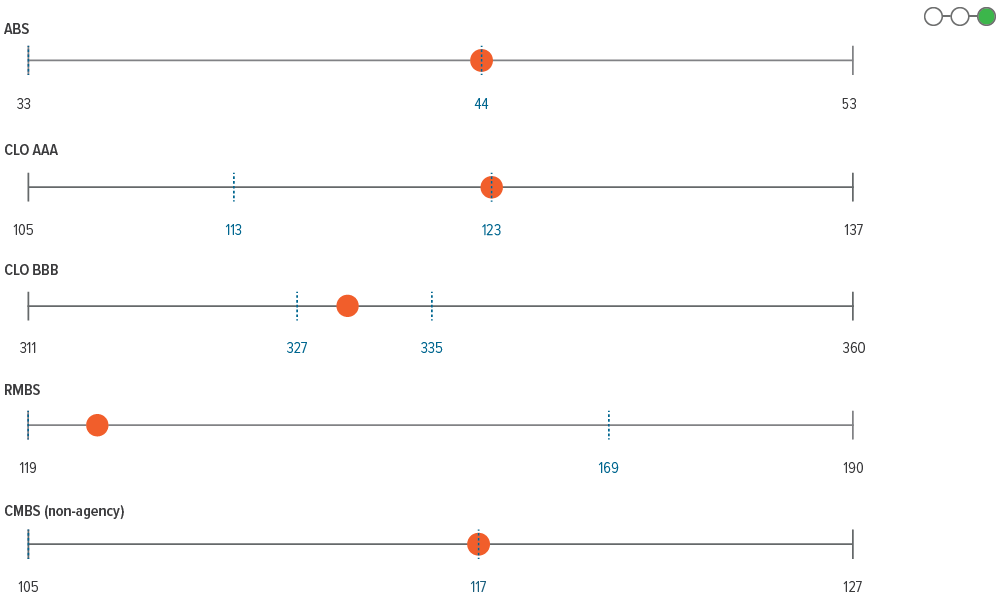
- Securitized credit remains positive overall, led by mortgage credit and consumer ABS.
- Mortgage credit remains positive, supported by accumulated home price appreciation, demographics, a roughly 3-million-unit housing shortage, and durable labor market support, while improving valuations and a shrinking forward supply pipeline strengthen the near-term setup.
- Consumer ABS remains positive, as strong risk appetite and resilient labor markets are supported by technicals that absorbed the post-Labor Day supply surge, while K/E-shaped consumer stress remains a headwind.
- CLOs remain mixed, with tight IG tranche valuations and AI/SaaS disruption risk offset partly by strong floating-rate demand and supportive technicals.
- CMBS could be pressured by elevated rates, but early-cycle dynamics and the lack of new property type stress should limit the overall impact.
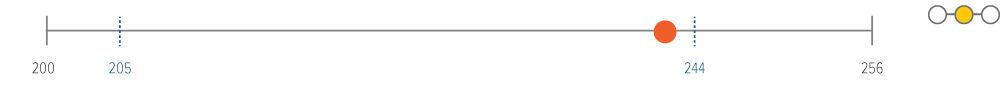
- Emerging market hard currency debt remains neutral, as tight spreads are offset by resilient global growth and elevated absolute yields.
- September spreads widened by around 15 bp for both sovereigns and corporates, but they remain near historically tight levels.
- Positioning favors corporates and quasis, Latin America, and BBB/BB quality, while remaining underweight sovereigns, cyclical corporates, Asia, GCC exposure, and A-rated risk; the main risk is that higher U.S. real rates, a stronger dollar, and a more hawkish Fed overshadow solid EM fundamentals.
A note about risk: The principal risks are generally those attributable to bond investing. Holdings are subject to market, issuer, credit, prepayment, extension, and other risks, and their values may fluctuate. Market risk is the risk that securities may decline in value due to factors affecting the securities markets or particular industries. Issuer risk is the risk that the value of a security may decline for reasons specific to the issuer, such as changes in its financial condition. The strategy invests in mortgage-related securities, which can be paid off early if the borrowers on the underlying mortgages pay off their mortgages sooner than scheduled. If interest rates are falling, the strategy will be forced to reinvest this money at lower yields. Conversely, if interest rates are rising, the expected principal payments will slow, thereby locking in the coupon rate at below market levels and extending the security’s life and duration while reducing its market value.